

If you follow the news, you have likely heard about new legislation radically altering the rules for TVDE operators. Among business owners, an understandable alarm has arisen regarding the legal viability of the vehicles currently on the road. The new Law no. 59/2026 decrees the end of one of the most common and convenient practices in the sector: using vehicles under "comodato" (free loan) contracts. To ensure your company is not caught off guard, we have prepared a clear guide on what truly changes, the transition deadlines in force, and how you should prepare. What happens in practice? Until now, many operators built their fleets using third-party vehicles, quickly legalising operations through a "comodato" contract (a free loan). The new law explicitly prohibits the use of this mechanism for TVDE activity, requiring fleets to prove business risk. Your company will be forced to replace these links with direct acquisition, Leasing, or Renting. In accounting, the impact is immediate and transformative. Replacing free contracts with commercial contracts forces rental payments, completely altering your company's balance sheet structure and financial ratios. The Transition Deadline: Until the end of the year The restriction applies not only to new registrations, but to all vehicles currently operating. The law established a maximum transition period of 120 days from its entry into force (September 1, 2026) to regularise the entire fleet. This means your company has only until the end of the year to convert all "comodato" agreements into legal commercial contracts. The risk of immediate blocking by platforms The legislator left no room for informality and placed the burden of enforcement directly on the platforms (such as Uber or Bolt). Once the transition period ends, platforms are obliged to verify the legality of each vehicle's contract. Any car remaining registered under a "comodato" contract will be blocked and disconnected from the application. Summary of Differences For a quick decision, here is how the two options compare side by side: What is it in practice? Comodato Agreement (Outlawed): Gratuitous loan of the vehicle Renting / Leasing (Mandatory): Commercial rental or financial leasing agreement Current Application Comodato Agreement (Outlawed): Expressly prohibited in TVDE Renting / Leasing (Mandatory): Approved and required by law Cash Flow Impact Comodato Agreement (Outlawed): Nil (no monthly fee) Renting / Leasing (Mandatory): Requires the payment of fixed monthly rents Where does it sit on the Balance Sheet? Comodato Agreement (Outlawed): No direct impact Renting / Leasing (Mandatory): Increases operating costs (Renting) or Assets/Liabilities (Leasing) How should your company prepare right now? The era of informal fleet structures has come to an end. To protect your company from fines and litigation, adopting the following measures is essential: TVDE Fleet Audit: Immediately identify all vehicles operated by your company that are not your property nor covered by a financial leasing or operational rental contract. Treasury Impact Assessment: Calculate the impact that new renting or leasing rents will have on fixed costs and monthly tax deductions. Anticipate Financial Bureaucracy: Approving credit contracts (Leasing/Renting) with banks and leasing companies takes time. Initiate contract changes before the 120-day deadline expires and blockages take effect. Before proceeding to sign new contracts or execute any transfer, contact our office. Our Accounting team is available to audit your processes and classify the operation in the most advantageous way for your taxes. Talk to us.
Building your own home is a lifetime project, but the tax burden has historically weighed disproportionately on self-construction. With the entry into force of the new Housing Package (Decree-Law no. 97/2026), the landscape has changed: the State created a partial VAT refund scheme for individuals building their own primary residence. In practice, the State commits to refunding the difference between standard VAT (23%) paid to the contractor and the reduced rate (6%). However, simply keeping receipts in a drawer is not enough. This is a demanding tax benefit, with valuation limits and exclusions that require planning from day one of construction. Here are the rules to ensure you receive this refund from the Tax Authority: 1. Who Qualifies and What is the Maximum Ceiling? This scheme is exclusive to natural persons (individuals) acting outside the scope of a business or professional activity. The property under construction must be strictly intended for Primary Residence (Habitação Própria e Permanente - HPP). To avoid subsidizing luxury housing, the legislator imposed a "moderate value" limit: total cost (Land Acquisition Value + Construction Costs) or the final Tax Asset Value (VPT), whichever is higher, cannot exceed €660,982. If your house exceeds this threshold, all rights to any refund are lost. 2. The Major Alert: What Counts for the Refund? The biggest risk for families in self-construction is assuming they can buy materials directly at retail stores to deduct VAT. The law is categorical: What is eligible: Only VAT (at 23%) borne on construction service invoices issued by contractors, properly reported on e-fatura. What is excluded: Isolated purchases of building materials (if bought directly by the owner at retail stores) do NOT grant refund rights. The same applies to simple renovation works (the regime requires new construction or prior total demolition). 3. Residency Retention Rules (The Retention Period) Similar to capital gains regimes, the State demands real proof that the house serves as the family's residence. Following the issuance of the "start of use" document by the Municipal Council, the owner must meet two deadlines: You have six months to allocate the property as your HPP, proven by updating your fiscal address with the Tax Authority. You must maintain that fiscal address and reside in the house for a minimum period of 12 months (barring rare exceptions linked to sudden family changes, such as divorce or an increase in the number of children). Failure to comply with these rules gives the Tax Authority power to demand full repayment of the refunded money, plus interest. 4. How and When to Request the Money Back? You do not have to wait for the annual IRS tax return. The refund request is made exclusively online, in a dedicated area of the Portal das Finanças, and has a strict deadline: 12 months following the issuance of the property's start of use documentation. Upon application, you must attach property identification, executed written construction contracts, proof of land acquisition value, and all invoices. If properly submitted, the Tax Authority has 150 days to deposit the VAT refund directly into your bank account (IBAN). If you are planning to build your own home, do not sign contracts with your builder without consulting. How materials and labor are invoiced makes the difference between recovering tens of thousands of euros or losing the benefit entirely.
New housing legislation (Decree-Law no. 97/2026) did not only adjust VAT and IRS. Municipal Property Transfer Tax (IMT) underwent one of the most pragmatic overhauls in recent years, designed to curb external speculation, accelerate State collection, and reward acquisitions at controlled costs. If you plan to buy or sell a home, or if you manage foreign clients in your real estate portfolio, these are the three critical changes that will impact cash flow in your next transaction: 1. The Curb on Non-Residents (Fixed 7.5% Rate) The legislator created a clear disincentive for home purchases by foreign investors. In the acquisition of urban buildings or units intended exclusively for housing by non-resident buyers, the maximum flat rate of 7.5% invariably applies. At the initial purchase stage, there is no entitlement to exemptions or rate reductions. However, the State permits the cancellation and refund of overpaid tax if the buyer fulfills one of the following criteria: Becomes a tax resident in Portugal within a maximum of two years after acquisition. Proves that they had already been considered a tax resident in Portugal in the past. Allocates the property to the residential rental market at moderate rent (not exceeding legal limits, capped at €2,300 per month in 2026) within six months of purchase, and maintains it effectively rented for at least 36 months during the first five years. In these regularisation scenarios, the owner has six months (counting from the date they become resident or sign the lease agreement) to request the tax difference refund from the Tax Authority. 2. The Bonus for Cost-Controlled Housing (Habitações de Custos Controlados - HCC) In contrast to the surcharge on external investment, the decree introduced benefits for those acquiring a Primary Residence (HPP) classified as Cost-Controlled Housing. The acquisition is exempt from IMT provided the property value does not exceed the limit of the 1st tax bracket (which, in 2026, stands at €330,539). If the purchase value exceeds this threshold, the excess benefits from reduced rates applicable under IMT Jovem. Buyers also gain entitlement to a tax deduction against Stamp Duty (Imposto do Selo) borne on the acquisition. The "fine print" you cannot ignore: to access this benefit in HCC, the law dictates that the buyer must not have been the holder of property rights (or any partial figure of that right) over any residential property in the three years preceding the purchase date. The real estate market in 2026 leaves no room for improvisation at the deed signing. Whether structuring the sale of a property portfolio to foreign clients or planning your own acquisition to avoid surprises with new rates and settlement deadlines, our team provides proper guidance at the time of acquiring your property.
The cost of construction contracts has been one of the biggest bottlenecks for real estate developers and promoters. Aiming to boost supply, the new Housing Package (Decree-Law no. 97/2026) introduced a major measure: Item 2.42 of List I attached to the VAT Code, which allows applying the reduced rate (6%) to construction or rehabilitation contracts. However, dropping the tax from 23% to 6% on a project worth hundreds of thousands of euros is not automatic. The Tax Authority defined strict rules and red lines that, if crossed, force the developer to refund the tax with interest. If you have projects in the pipeline, here is the roadmap to secure this savings safely: 1. Purpose and Value Limits Your building or unit only qualifies for the 6% rate if it is allocated to one of two very specific purposes: Sale for Primary Residence (Habitação Própria e Permanente - HPP): The final sale price cannot exceed the maximum value of the 2nd IMT bracket, which in 2026 is fixed at €660,982. Residential Rental: The rent amount cannot exceed 2.5 times the Minimum Wage, which equates to a cap of €2,300 per month in 2026. (Note: If a single building contains both eligible residential apartments and commercial shops, the 6% rate only applies to the proportion of the contract corresponding to the eligible residential area. The remainder pays 23%.) 2. The Deadline Clock Building with 6% VAT requires placing the property on the market quickly. From the moment the "start of use" document (documento de início de utilização) is issued by the Municipal Council, the clock starts ticking: You have 24 months to execute the deed of sale or to bring the first lease agreement into force. In the case of rental, a "retention period" applies: the property must be effectively rented for at least 36 months (consecutive or interpolated) during the first 5 years. 3. Who is at Fault if Rules Fail? This is the concern that has most alarmed real estate promoters: What if I build at 6% and, in the end, sell the house to someone who turns it into Local Accommodation or a holiday home? The law surgically separated responsibilities: Promoter's Fault: If you sell the property for more than €660,982, fail the 24-month deadline, or forget to explicitly state in the deed that the property was constructed under "Item 2.42.1". In these cases, the promoter must submit a replacement declaration and pay the State the VAT difference (from 6% to 23%), plus heavy compensatory interest. Buyer's Fault: If the promoter complies with price caps and inserts all terms correctly in the deed, but the buyer breaks the promise and does not move in within six months, the construction VAT is unaffected. The penalty falls exclusively on the buyer, who will face an IMT surcharge corresponding to 10% of the property value. The Window of Opportunity: To benefit from this regime, your project's licensing request (or prior communication) must be submitted to the Municipal Council between September 25, 2025, and December 31, 2029. Structuring VAT in a real estate project often dictates the viability of the entire business. Before launching your next construction contract and signing agreements with builders, speak with our team. We support your company through budget and accounting planning to safeguard your tax benefit.
From now on, if your company awards a construction contract and the contractor does not hold a valid contractor's license (alvará) or construction certificate issued by the IMPIC, the VAT reverse charge rule (IVA - Autoliquidação) no longer applies. This is the change with the highest immediate impact on daily operations and company cash flow, introduced by the newly approved Housing Package (Decree-Law no. 97/2026). Many companies became accustomed to billing repair, remodeling, or painting services with the mention "IVA - Autoliquidação," even without being formally registered construction firms. The Tax Authority put an end to this practice. For the reverse charge to occur — meaning the service provider bills without VAT and the client assumes tax assessment —, the builder MUST hold a public or private works contractor's license or certificate. If they do not, they are obliged to bill with standard VAT, forcing the entity awarding the work to pay the tax upfront. The second major update in this legislative package is excellent news for real estate promoters and residential leasing businesses. Until now, as entities carrying out exclusively tax-exempt operations (without the right to deduct VAT), these companies always received construction invoices with tax charged upfront by the builder. Under the new law, the reverse charge mechanism now also applies to these tax-exempt companies, but only in a very specific scenario: when contracts are intended for properties for sale (Primary Residence - HPP) or for residential lease framed under the new reduced rate, Item 2.42. In practice, this means the work must respect strict "moderate value" limits, such as charging rents that do not exceed €2,300 per month in 2026. If your residential leasing company awards one of these eligible contracts: The builder (holding the respective IMPIC license) issues the invoice without VAT, stating "IVA - Autoliquidação". Your company, despite not carrying out VAT-taxable activities, must submit a periodic VAT return by the end of the following month to declare and pay this self-assessed tax to the State. The major financial advantage is that this tax is self-assessed directly at the new reduced rate applicable under Item 2.42, drastically lowering the net cost of the construction work. These rules formally enter into force on July 1, 2026, but can be applied with retroactive effect to invoices issued since January 1, 2026, provided there is mutual agreement between the contractor and the client. As these new rules intersect real estate price caps with formal licensing requirements, an improper reverse charge can be costly in fines and compensatory interest.
The State machine requires speed, and the new Decree-Law no. 177/2026 responds to this urgency with a profound revision of the Public Contracts Code (CCP). Aiming to reduce bureaucracy and stimulate investment, the legislator substantially raised the thresholds allowing public entities to award contracts faster and in a more simplified manner. If your company supplies goods, provides services, or executes public works for municipal councils, public institutes, or ministries, the rules of the game change radically starting October 1, 2026. The difference between the old and new limits opens a massive window of opportunity. Here is what changes in procurement: 1. Acquisition of Goods and Services The caps for purchasing equipment, materials, or service provision (from consulting to cleaning) underwent a very significant increase, allowing the State to use direct invitations for much higher amounts: Direct Award (Ajuste Direto - 1 invitation): The limit jumps from the previous €20,000 to €75,000. Prior Consultation (Consulta Prévia - Minimum 3 invitations): The limit rises from €75,000 to €130,000. 2. Public Works Contracts (Empreitadas de Obras Públicas) In the construction sector, the need to accelerate project execution led the legislator to multiply the margin to avoid lengthy public tenders: Direct Award: It is now possible to directly select a contractor for works with an estimated value below €150,000 (the previous limit was merely €30,000). Prior Consultation: The State can now invite three companies for works whose estimated value falls below €1,000,000 (a substantial leap compared to the old €150,000 cap). 3. The New "Special Prior Consultation" (Consulta Prévia Especial) In addition to the general rise in limits, the decree introduced an accelerated regime for critical and strategic projects. The new "Special Prior Consultation" allows awarding contracts through direct invitation to at least five entities for values up to €2,000,000. This exceptional ceiling applies exclusively to rapid investment fronts, such as: Projects financed by European funds. Promotion of public or affordable housing. Works or acquisitions for the health sector, care homes, and social support. Digital transformation projects (acquisition of software, equipment, and cloud services). 4. Less Paperwork: Exemption from Written Contracts To accompany the rise in limits and ensure execution does not hit contractual bureaucracy, the legislator doubled the threshold where a formal written contract is not required: Goods and Services: The formal contract exemption limit rises from €10,000 to €30,000. Works (Empreitadas - of very low complexity): The limit rises from €30,000 to €75,000. The Opportunity for SMEs: The massive rise in Direct Award and Prior Consultation thresholds represents an excellent opportunity for small and medium-sized enterprises to join the State's supplier pool with far less bureaucratic friction and without the complexity of public tenders. However, direct invitations require your company to be on the "front line," with all professional qualification documents and tax/social security regularity immaculate. If you intend to bill the public sector under these new rules, our team can help you organize your administrative structure and ensure compliance with all CCP requirements. Contact us to prepare your company for the public market.
Although Portugal has finally initiated a downward trajectory for Corporate Income Tax (IRC) rates, the tax burden goes far beyond the percentage applied to profits. According to recent data from the Tax Competitiveness Observatory, managed by Deloitte, around 60% of Portuguese companies still classify our tax system as highly complex and a direct barrier to attracting investment. The Problem Isn't Just the Rate; It's the Complexity The diagnosis shared by managers is clear. Current frustration no longer stems exclusively from the amount of tax payable, but from "compliance costs". Constant legislative instability, the slow pace of tax justice, and the density of regulations demand an administrative effort disproportionate to Small and Medium-sized Enterprises (SMEs). Instead of focusing their energy on innovation, seeking new clients, or business expansion, entrepreneurs feel they are wasting valuable time and resources trying to interpret and comply with the bureaucratic demands of the Tax Authority. Simplify Management with Cooperate This study validates a frustration that many managers experience daily: the system is difficult to navigate alone. The tax machine will not simplify overnight, but the way your company deals with it can — and should — change radically. At Cooperate , we understand that bureaucracy steals your most valuable resource: time. We act as your tax shield and translator. We transform legislative confusion into financial predictability and ensure that your company meets all obligations without setbacks and with maximum tax efficiency. We take on the burden of complexity so that your sole focus is the profitable growth of your business. Speak with us today and bring peace of mind to your management.
W hen climate catastrophes, such as floods or storms, strike a busin ess, the entrepreneur's priority is clear: rebuild the facilities and resume invoicing as quickly as possible. To address this urgency, the Banco Português de Fomento (BPF) has launched the Reconstruction Support Line , introducing unprecedented financial agility. Fast Capital, Immediate Works Available through Commercial Banking, this funding line covers up to 100% of validated losses. Crucially, insurance payments are deducted subsequently, ensuring you do not have to wait for slow appraisal processes before starting reconstruction. The State’s major breakthrough accompanying this funding is the elimination of bureaucratic barriers. To accelerate the start of work, a simplified regime has been created that exempts companies from time-consuming administrative controls, such as standard municipal urban licensing. In practice, this means an end to the frustrating wait for bureaucracy to repair your infrastructure. Speed Requires Banking Preparation However, the exemption from municipal licensing does not negate the rigour required by banks and the BPF. To access this line with subsidised rates and a State guarantee, the documentation of damages, the accounting framework, and the structure of the credit application must be flawless. This is where a strategic financial partner makes the difference. At Cooperate , we understand that in times of crisis, your focus must be on operations and your team. We handle the technical negotiations for you. We help your company structure the validation of losses, prepare the financial dossier required by the Development Bank, and monitor the application swiftly and securely. Do not let a documentation failure delay your fresh start. Contact us today to secure the capital needed to rebuild your business.
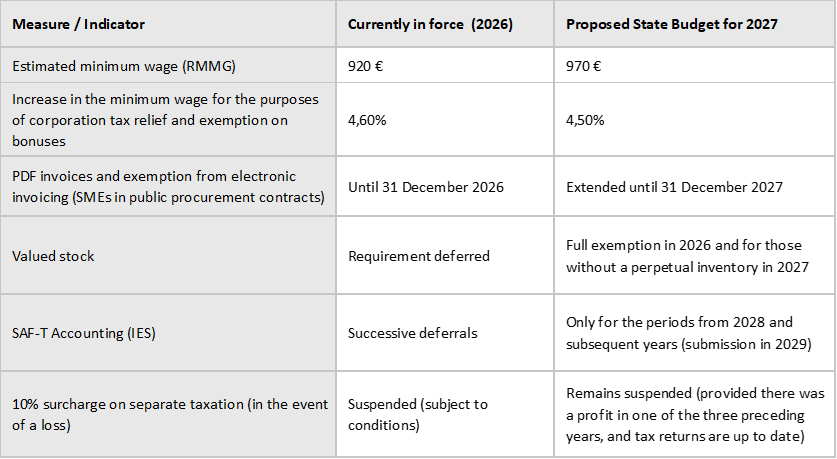
During periods of market contraction or intensive investment, reporting a tax loss is a significant management challenge in itself. Historically, legislation placed further strain on cash flow during these critical times: companies reporting a loss faced an automatic 10-percentage-point penalty on Autonomous Taxation (AT) . This applied to daily operational overheads such as company vehicles, subsistence allowances, and representation expenses. The excellent news for the business community is that the 2026 fiscal framework has suspended this penalty. What does this mean for your cash flow? This tax relief ends the "double penalty" long dreaded by business owners. If your company has faced an atypical year—whether due to a drop in sales or a significant financial effort that resulted in an accounting loss—you will no longer be penalised with a disproportionate tax bill on your operating costs. The funds previously earmarked for this extra tax remain in your bank account. This provides vital financial oxygen , allowing you to focus your energy on recovery and the growth of your commercial activity. Safeguard Your Business with Cooperate While legislation provides relief, accounting precision is what truly protects your company. The correct classification of invoices and the rigorous assessment of expenses subject to Autonomous Taxation are essential to avoid complications with the Tax Authority. At Cooperate , we master the tax code to use it in your business's favour. We ensure your cost structure is optimised and that your company benefits from all legal exemptions, protecting your liquidity when you need it most. Contact us today to ensure intelligent, hassle-free tax management.
The uncertainties surrounding the execution of European funds have been resolved. The "Recuperar Portugal" Mission Structure recently submitted a strategic reprogramming of the Recovery and Resilience Plan (RRP/PRR) to the European Commission, guaranteeing 100% execution.