

Although Portugal has finally initiated a downward trajectory for Corporate Income Tax (IRC) rates, the tax burden goes far beyond the percentage applied to profits. According to recent data from the Tax Competitiveness Observatory, managed by Deloitte, around 60% of Portuguese companies still classify our tax system as highly complex and a direct barrier to attracting investment. The Problem Isn't Just the Rate; It's the Complexity The diagnosis shared by managers is clear. Current frustration no longer stems exclusively from the amount of tax payable, but from "compliance costs". Constant legislative instability, the slow pace of tax justice, and the density of regulations demand an administrative effort disproportionate to Small and Medium-sized Enterprises (SMEs). Instead of focusing their energy on innovation, seeking new clients, or business expansion, entrepreneurs feel they are wasting valuable time and resources trying to interpret and comply with the bureaucratic demands of the Tax Authority. Simplify Management with Cooperate This study validates a frustration that many managers experience daily: the system is difficult to navigate alone. The tax machine will not simplify overnight, but the way your company deals with it can — and should — change radically. At Cooperate , we understand that bureaucracy steals your most valuable resource: time. We act as your tax shield and translator. We transform legislative confusion into financial predictability and ensure that your company meets all obligations without setbacks and with maximum tax efficiency. We take on the burden of complexity so that your sole focus is the profitable growth of your business. Speak with us today and bring peace of mind to your management.
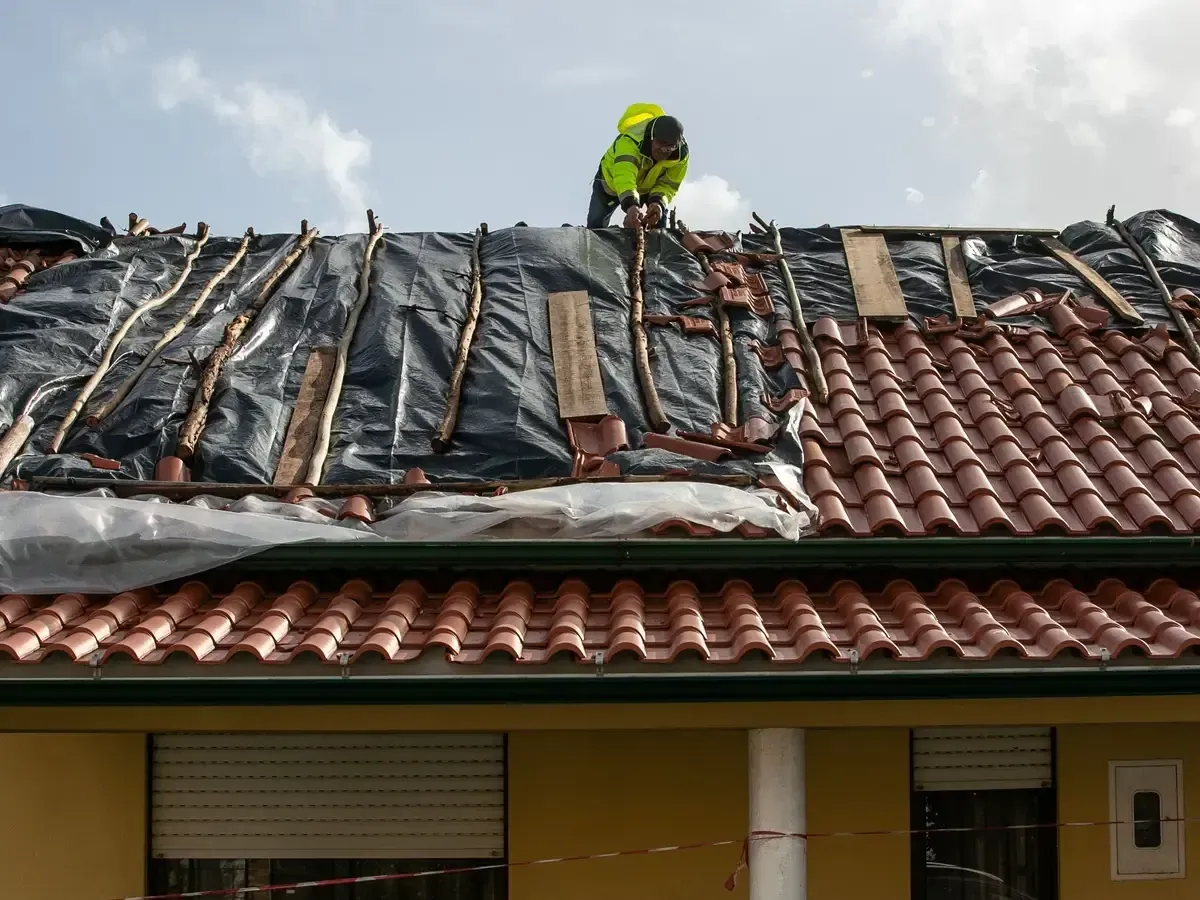
W hen climate catastrophes, such as floods or storms, strike a busin ess, the entrepreneur's priority is clear: rebuild the facilities and resume invoicing as quickly as possible. To address this urgency, the Banco Português de Fomento (BPF) has launched the Reconstruction Support Line , introducing unprecedented financial agility. Fast Capital, Immediate Works Available through Commercial Banking, this funding line covers up to 100% of validated losses. Crucially, insurance payments are deducted subsequently, ensuring you do not have to wait for slow appraisal processes before starting reconstruction. The State’s major breakthrough accompanying this funding is the elimination of bureaucratic barriers. To accelerate the start of work, a simplified regime has been created that exempts companies from time-consuming administrative controls, such as standard municipal urban licensing. In practice, this means an end to the frustrating wait for bureaucracy to repair your infrastructure. Speed Requires Banking Preparation However, the exemption from municipal licensing does not negate the rigour required by banks and the BPF. To access this line with subsidised rates and a State guarantee, the documentation of damages, the accounting framework, and the structure of the credit application must be flawless. This is where a strategic financial partner makes the difference. At Cooperate , we understand that in times of crisis, your focus must be on operations and your team. We handle the technical negotiations for you. We help your company structure the validation of losses, prepare the financial dossier required by the Development Bank, and monitor the application swiftly and securely. Do not let a documentation failure delay your fresh start. Contact us today to secure the capital needed to rebuild your business.
During periods of market contraction or intensive investment, reporting a tax loss is a significant management challenge in itself. Historically, legislation placed further strain on cash flow during these critical times: companies reporting a loss faced an automatic 10-percentage-point penalty on Autonomous Taxation (AT) . This applied to daily operational overheads such as company vehicles, subsistence allowances, and representation expenses. The excellent news for the business community is that the 2026 fiscal framework has suspended this penalty. What does this mean for your cash flow? This tax relief ends the "double penalty" long dreaded by business owners. If your company has faced an atypical year—whether due to a drop in sales or a significant financial effort that resulted in an accounting loss—you will no longer be penalised with a disproportionate tax bill on your operating costs. The funds previously earmarked for this extra tax remain in your bank account. This provides vital financial oxygen , allowing you to focus your energy on recovery and the growth of your commercial activity. Safeguard Your Business with Cooperate While legislation provides relief, accounting precision is what truly protects your company. The correct classification of invoices and the rigorous assessment of expenses subject to Autonomous Taxation are essential to avoid complications with the Tax Authority. At Cooperate , we master the tax code to use it in your business's favour. We ensure your cost structure is optimised and that your company benefits from all legal exemptions, protecting your liquidity when you need it most. Contact us today to ensure intelligent, hassle-free tax management.
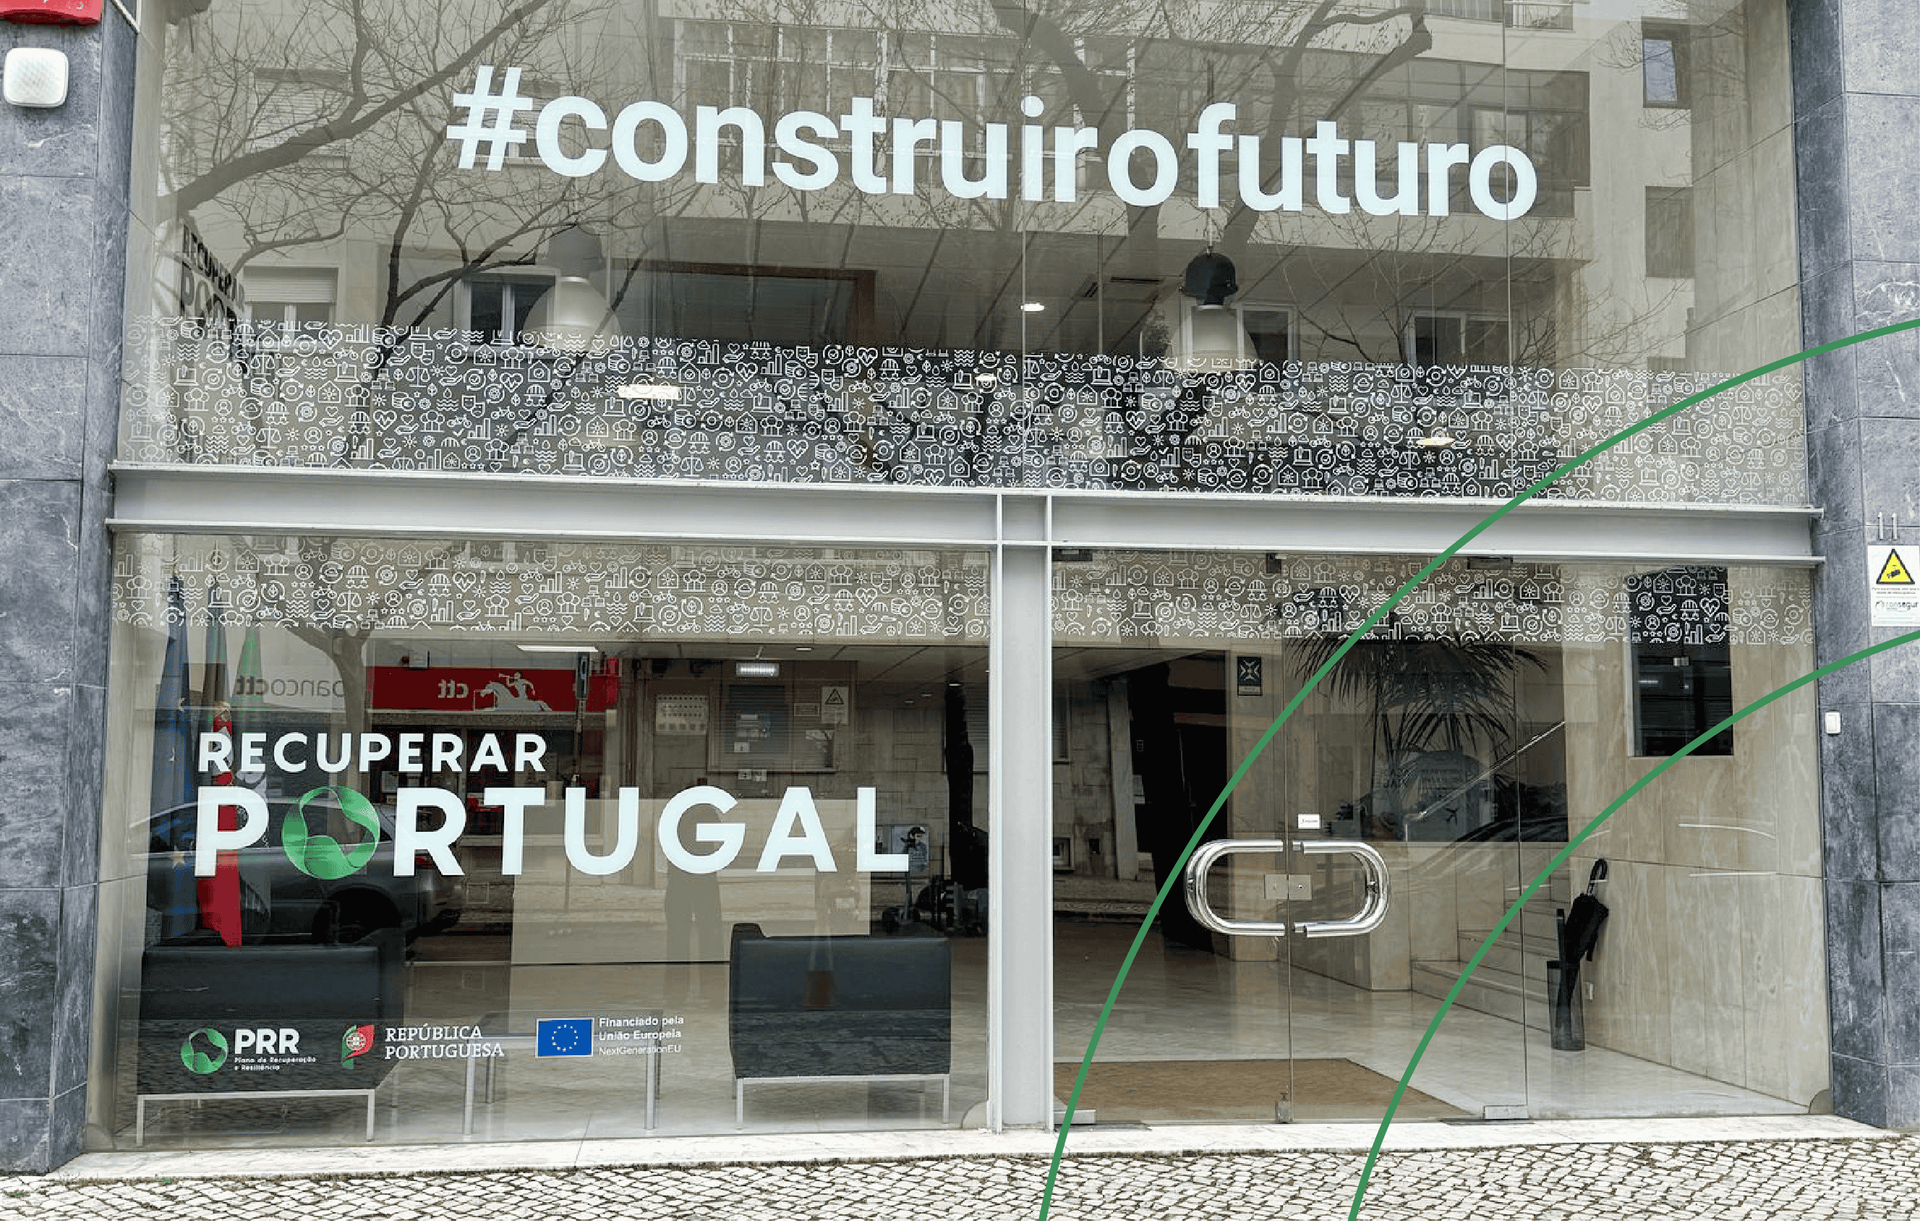
The uncertainties surrounding the execution of European funds have been resolved. The "Recuperar Portugal" Mission Structure recently submitted a strategic reprogramming of the Recovery and Resilience Plan (RRP/PRR) to the European Commission, guaranteeing 100% execution.
Finding talent and expanding your team is essential for business growth, but the weight of salaries and Social Security contributions (TSU) is a constant challenge. The good news? The IEFP (Institute for Employment and Vocational Training) has updated the limits for direct hiring incentives for 2026, driven by the Social Support Indexer (IAS) being set at €537.13. If you are planning to recruit, this is an opportunity to drastically reduce costs during the first year of the contract. These non-repayable grants help subsidise the new employee's salary. Two main measures stand out: 1. "Emprego +Talento": Focused on young professionals up to 35 years old with higher education (Bachelor’s, Master’s, or PhD). The base support for your company now exceeds €9,600. 2. "+Emprego": Supports the permanent hiring of unemployed individuals registered with the IEFP. In this case, the base funding allocated exceeds €6,400. Maximise Your Savings: These base amounts can further benefit from bonuses of up to 35% if specific criteria are met, such as hiring long-term unemployed individuals or creating jobs in the country's inland regions. Turn Legislation into Savings with Our Support While highly attractive, these incentives require compliance with strict administrative and bureaucratic rules, such as maintaining employment levels. At Cooperate , we go beyond processing payroll. Before you recruit, we simulate the real cost of hiring, identify the most advantageous measure, and manage the entire IEFP application process on your behalf. Contact us today to secure the talent you need with full financial security.